
Severe Kenya Airways capacity constraints have pushed Kenya’s national carrier down to sixth place in African airline rankings by passenger traffic. According to Business Daily reporter Vincent Owino, prolonged grounded aircraft shortages throughout 2025 and most of 2026 curtailed flight frequencies and eroded the airline’s continental market share.
The ranking slip underscores how global aviation supply-chain bottlenecks continue to reshape the East African aviation market. While regional rivals expanded seat supply to capture post-pandemic travel growth, Nairobi-based Kenya Airways (KQ) operated well below optimal capacity after engine and component delays sidelined key jets.
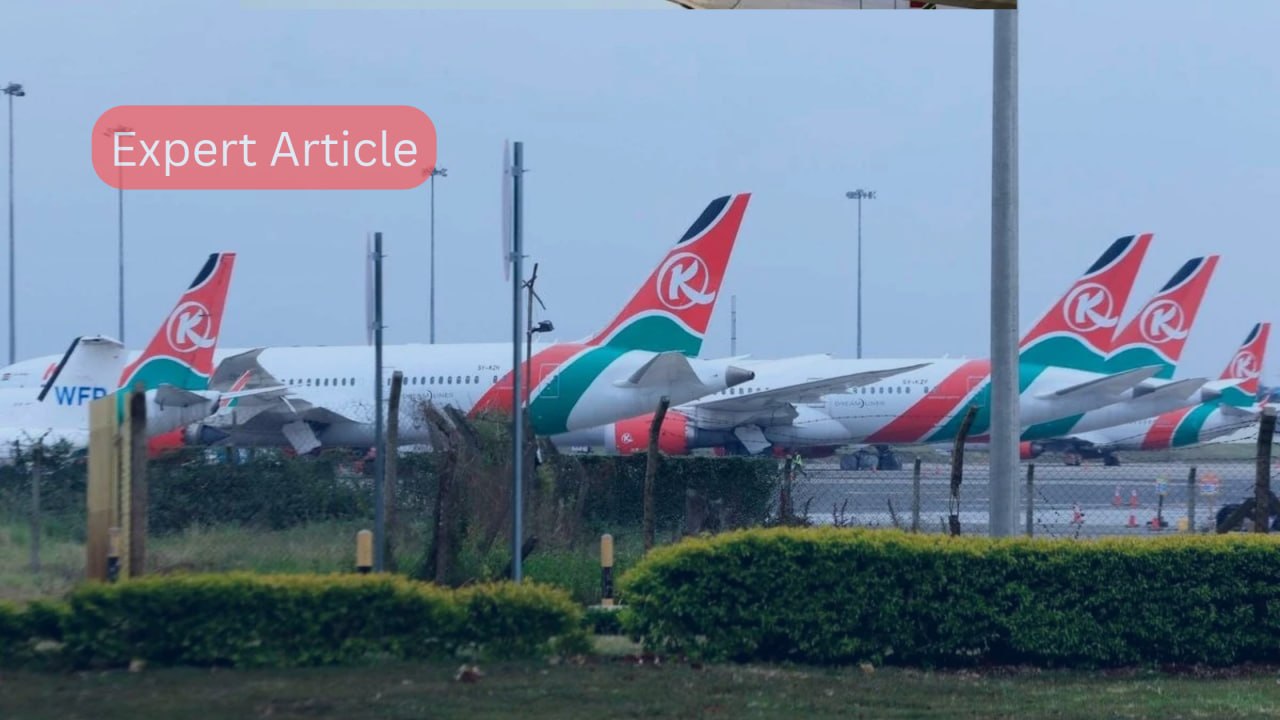
Aircraft availability has remained KQ’s primary operational hurdle over the past two years. In corporate disclosures, the airline confirmed that global shortages of engines and spare parts forced it to ground three of its nine wide-body Boeing 787 Dreamliners—a third of its long-haul fleet.
Those groundings directly reduced available seat kilometers and forced schedule adjustments across domestic, regional, and intercontinental routes. By June 2026, management reported that grounded planes were still cutting available seat capacity by 15% to 18%.
Shifting African Airline Rankings and Regional Competition
KQ’s capacity contraction occurred during a period of robust continental traffic growth. Data from the International Air Transport Association (IATA) shows that African airlines recorded an 8% year-on-year rise in international passenger demand in late 2026, supported by an 8.8% increase in regional seat capacity.
Because KQ could not add seats at the same pace, competing hubs captured greater market share. In neighboring Ethiopia, Ethiopian Airlines reinforced its position as Africa’s largest carrier, carrying 19 million passengers and generating $7.6 billion in revenue in its 2024/25 financial year.
North African carriers—including EgyptAir and Royal Air Maroc—alongside major South African operators also capitalized on steady fleet deployment. Separately, Skytrax’s 2026 passenger-satisfaction index placed Kenya Airways seventh in Africa, reflecting how fleet disruptions weighed on schedule reliability.
Policy Shifts and Grounded Aircraft Shortages Across Africa
Spare-part delays are not unique to Nairobi, as original equipment manufacturers worldwide face multi-year backlogs. In November 2026, neighboring Air Tanzania announced eight-day flight disruptions after engine shortages grounded three of its Airbus A220-300 aircraft.
To ease maintenance bottlenecks, regional aviation bodies have pushed for regulatory and fiscal reforms. The African Airlines Association (AFRAA) highlighted Kenya’s tax exemptions on aviation spare parts as a vital policy measure to lower maintenance costs and strengthen local Maintenance, Repair, and Overhaul (MRO) hubs.
At the same time, IATA continues to urge African governments to implement the Single African Air Transport Market (SAATM) and streamline visa rules. According to IATA’s 2026 Global Passenger Survey, restrictive entry requirements still deter 52% of African travelers from completing trips.
Industry Outlook: What’s Next for Kenya Airways?
Restoring grounded jets to active service remains the centerpiece of KQ’s turnaround strategy. In November 2026, Kenya’s Cabinet approved $350 million in shareholder financing to help the carrier meet urgent financial obligations and stabilize operations.
Management is also expanding third-party MRO capabilities at Jomo Kenyatta International Airport to position Nairobi as a regional maintenance hub. If global engine supply chains normalize in 2027 and KQ returns its full wide-body fleet to the skies, the carrier has room to reclaim lost passenger volume in the East African aviation market.
Sources