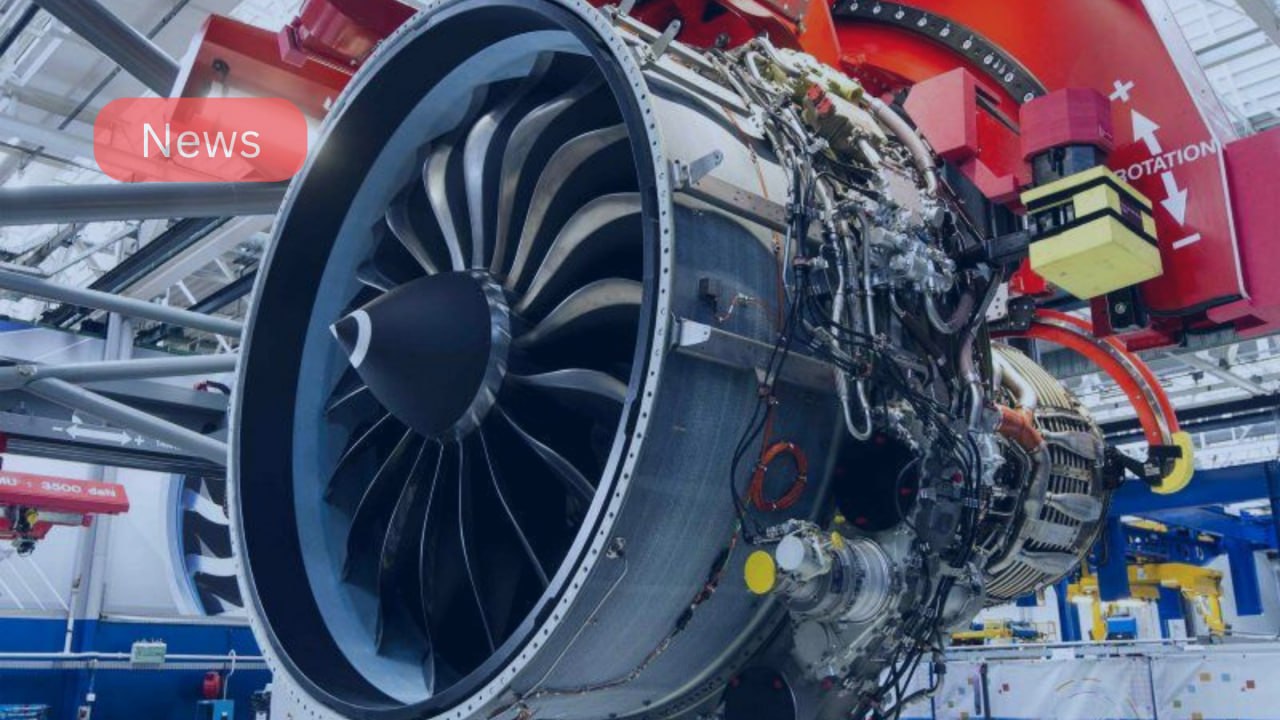

An analysis published on August 28, 2026, by Daniel Williams at Aviation Week Network reveals that commercial narrowbody engines monthly cycles are trending upward globally, demonstrating strong airline utilization despite persistent fuel price pressures. The evaluation of the primary single-aisle powerplants comes ahead of the AeroEngines Europe conference, where engine reliability and shop-visit bottlenecks remain top concerns.
Using real-time telemetry from the Aviation Week Intelligence Network (AWIN) Tracked Aircraft Utilization tool, the report tracks flight cycle metrics across the market’s primary narrowbody engines. According to Aviation Week analyst Daniel Williams, global demand for short-to-medium-haul air travel continues to drive heavy utilization of single-aisle fleets, forcing airlines to maximize engine cycles to maintain schedule integrity.
Narrowbody Engines Monthly Cycles Drive Maintenance Demand
While high jet fuel prices historically lead to capacity discipline, current market dynamics present a different picture. Airlines are operating higher narrowbody engines monthly cycles to accommodate strong passenger traffic and compensate for aircraft delivery delays from major manufacturers.
- High Aircraft Utilization: Both legacy platforms (such as the CFM56 and V2500) and next-generation turbofans (CFM LEAP and Pratt & Whitney GTF) are registering steady monthly flight hour gains.
- MRO Capacity Strain: Increased cycle accumulation is directly accelerating engine maintenance schedules, pushing shop visits into already congested maintenance, repair, and overhaul (MRO) facilities.
- Fleet Age Dynamics: Legacy narrowbody engines continue to handle a substantial share of total commercial flights, as airlines extend the service lives of older airframes to support flight schedules.
Regional Performance and Fleet Impacts
Data from aviation bodies such as the International Air Transport Association (IATA) confirms that domestic and intra-regional passenger routes lead global recovery metrics. Short-haul routes generate a higher ratio of flight cycles (takeoffs and landings) relative to flight hours compared to widebody long-haul operations.
As airlines absorb elevated jet fuel expenses, operating efficiency remains a balance between modern engine fuel burn advantages and the time-on-wing limitations of next-generation engines.
Industry Outlook: What’s Next for Narrowbody Fleet Maintenance?
As the commercial sector approaches the fourth quarter, engine utilization is expected to remain high. The persistent accumulation of flight cycles will test supply chains for critical engine components, including high-pressure turbine blades and compressor assemblies.
Airlines and lessors will need to balance tight flight schedules against scheduled engine shop visits. With engine shop visit forecasts reaching record highs across Europe and North America, engine turnaround times (TAT) will serve as the primary bottleneck determining single-aisle operational capacity heading into 2027.